All Categories
Featured

Evaluating PPO vs HMO Insurance
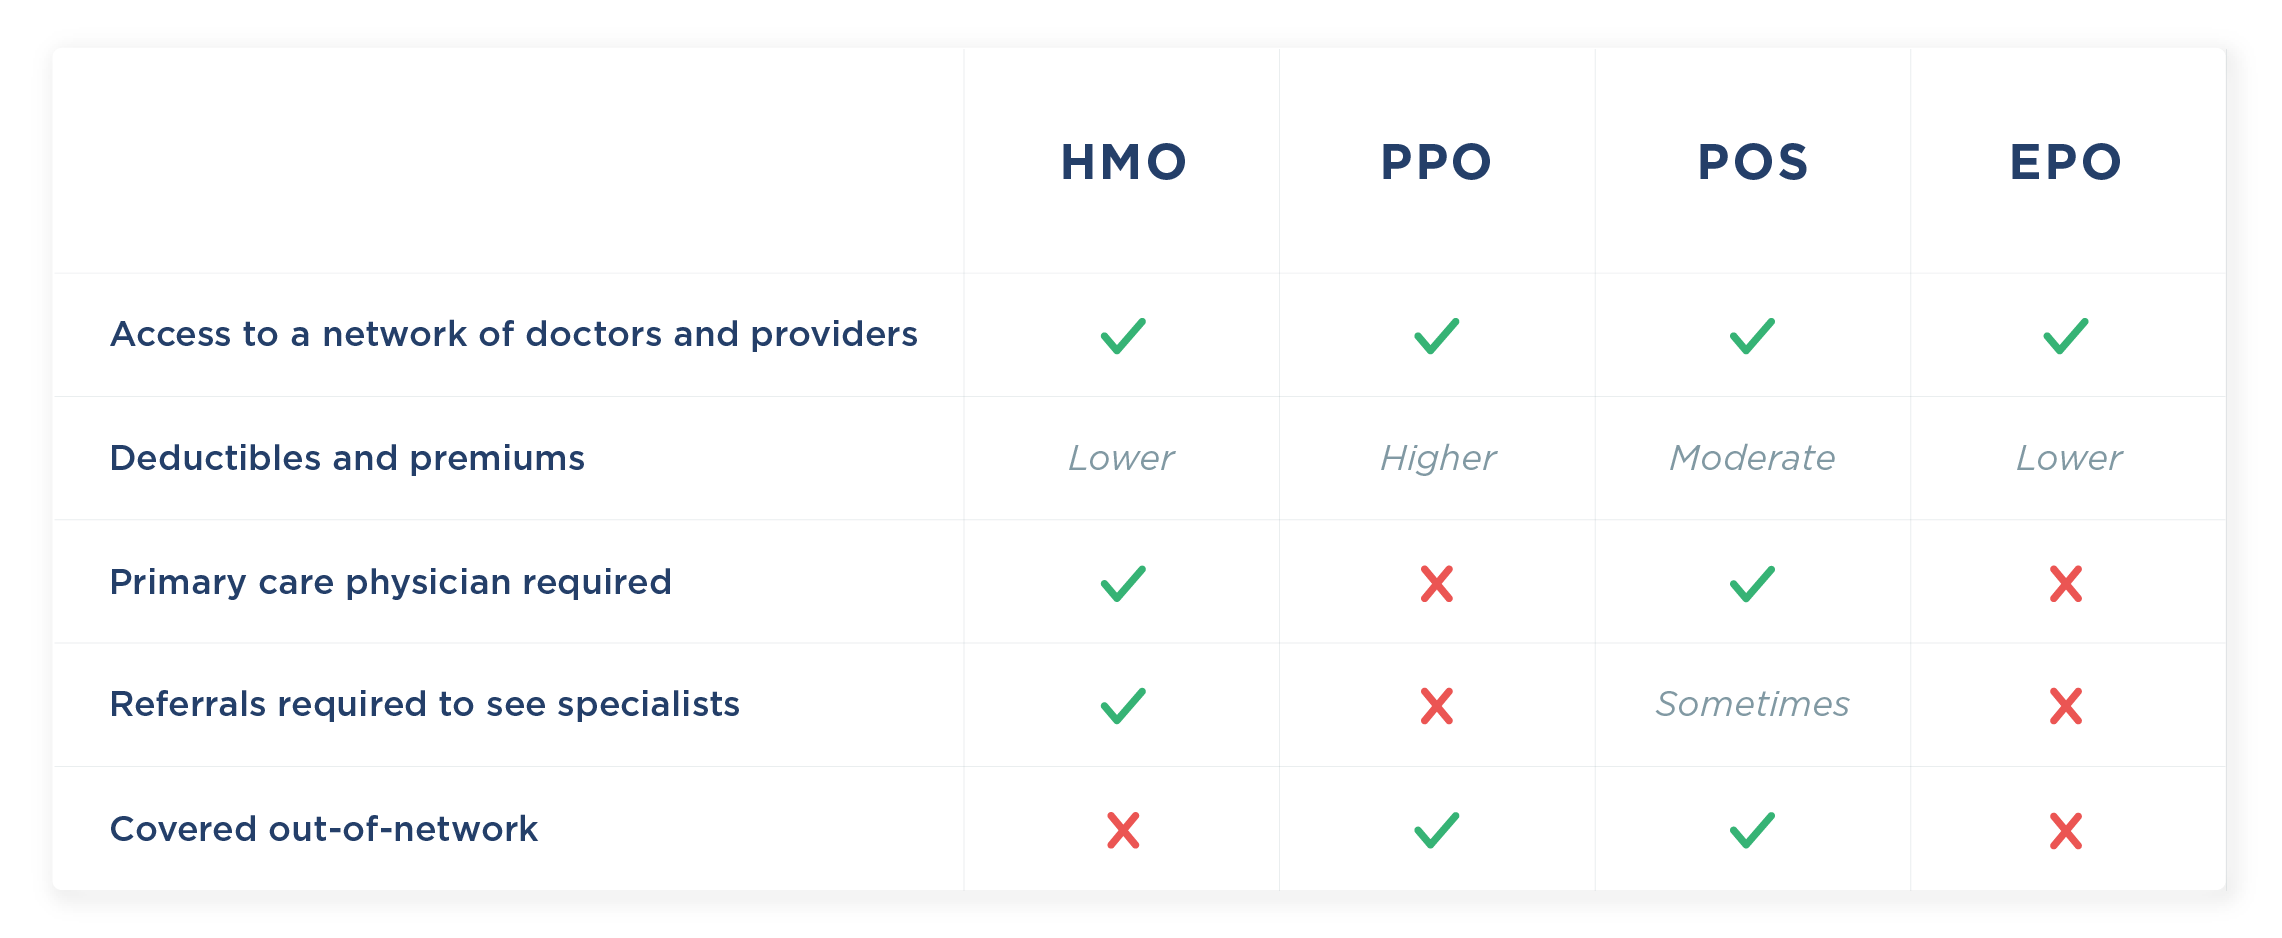
An HMO insurance coverage strategy is often considered as being more cost-efficient due to its lower monthly premiums and hassle-free due to its requirement that patients need to have a medical care doctor to manage their care. A PPO insurance coverage strategy is understood for its flexibility as it permits clients to manage their own care and look for different providers/specialists without needing a referral.
Comparable to basic insurance coverage plans, the two primary Medicare Benefit strategies are HMO and PPO.While HMO and PPO insurance prepares continue to be the most typical choice for patients to select from, there are a range of other insurance coverage choices. HMO and PPO insurance coverage strategies are the two most common healthcare insurance strategies in the United States.
While these insurance strategies are different, they are similar in the sense that they offer a client with a network of doctors, health centers, and other health care service providers that help members with their health-care journey. "HMO" serves as an acronym for "Health Upkeep Organization," while "PPO" functions as an acronym for "Preferred Company Company." An HMO insurance strategy is centered around a variety of healthcare facilities and health care service providers (described as an "HMO network") that have concurred to deal with clients within the network's insurance strategy. A referral is necessary for a client to see other professionals that are in-network or out-of-network, and frequently, receiving out-of-network care only occurs in emergency situation circumstances. This plan provides lower month-to-month premiums for its customers, making it an affordable insurance coverage choice.
Frequently, lower expenses for prescriptions. A patient can only see providers within the strategy's network unless they have a referral for an outside expert, or it's an emergency circumstance. Like an HMO strategy, a PPO insurance strategy provides a patient with a network (described as a "PPO network") of healthcare suppliers and health centers.
Essential Medicare Enrollment Advice in 2026
This strategy also lets the client coordinate their care and handle which providers they want to see, versus having a main care physician. The patient has more flexibility with which providers they pick to see, whether they're within the strategy's network or out-of-network. A lot of times, there is no need for a referral if a client cares to see an out-of-network expert.
The client is responsible for managing their healthcare, vice a medical care physician supervising. A 'service provider network' refers to the list of doctors, professionals, health centers, etc that an insurance firm contracts to supply medical services to its strategy members. Suppliers that are 'in-network' refer to the health care employees and medical facilities that are listed in the strategy.
The expenses associated with an HMO plan include deductibles, which is the quantity a patient need to pay before insurance contributions, and monthly premiums, which is the quantity taken out of a client's income. Typically, the month-to-month premiums gotten with an HMO plan are lower than a PPO plan's premiums.
Insurance in Montclair CA
Yearly, this led to a $6,869 coverage on people and $19,445 protection on households, revealing a lower month-to-month premium in contrast to a PPO plan type. A lot of times, the monthly premiums are taken out with a PPO strategy that is more costly than an HMO strategy's premiums.
Securing Coverage for Seniors
According to the Kaiser Household Foundation 2018 Health Benefits Survey, all companies utilizing a PPO insurance strategy paid $592 as the regular monthly premium on a specific and $1,694 as the month-to-month premium on a household. Annually, this resulted in a $7,149 protection on people and $20,324 coverage on families, showing a greater monthly premium in comparison to an HMO strategy type.
When trying to decide which strategy is best, there are lots of aspects to think about, with a few of the most important being versatility, cost effectiveness, and coordination of care. If it's flexibility that is crucial, then a PPO insurance coverage strategy may be a better suitable for they permit a client to have more control over which suppliers they see and when, no matter a recommendation.

Another advantage to an HMO plan is that it needs a patient to have a primary care doctor that coordinates their care for them. This implies that with a PPO insurance plan, the client will have to handle their own care and manage which providers/specialists they require to visit. In the end, one strategy is ruled out better than the other.
Health insurance strategies do not cover dental insurance. To find out more on obtaining an oral plan, such as a dental HMO strategy, 'DHMO strategy,' or an oral PPO plan, 'DPPO plan,' check out this resource. Once an American (who has actually been paying Medicare taxes for a minimum of 10 years) turns 65, they receive the health insurance plan understood as Medicare.

Latest Posts
Top IUL Plans for Wealth Growth
Final Expense Insurance Tips for Veterans

Key Strategies for 2026 Medicare Part D Enrollment